Neo Financial Review 2026 — Account, Fees & Rates
Our Verdict
Neo Financial brings together cashback credit cards, a Neo Chequing account with no monthly fees and a Neo Savings account that earns from 2% to 2.75% depending on the membership. Funds in these accounts are held in trust at CDIC member institutions and are eligible for CDIC protection up to $100,000; Neo itself is not a CDIC member.
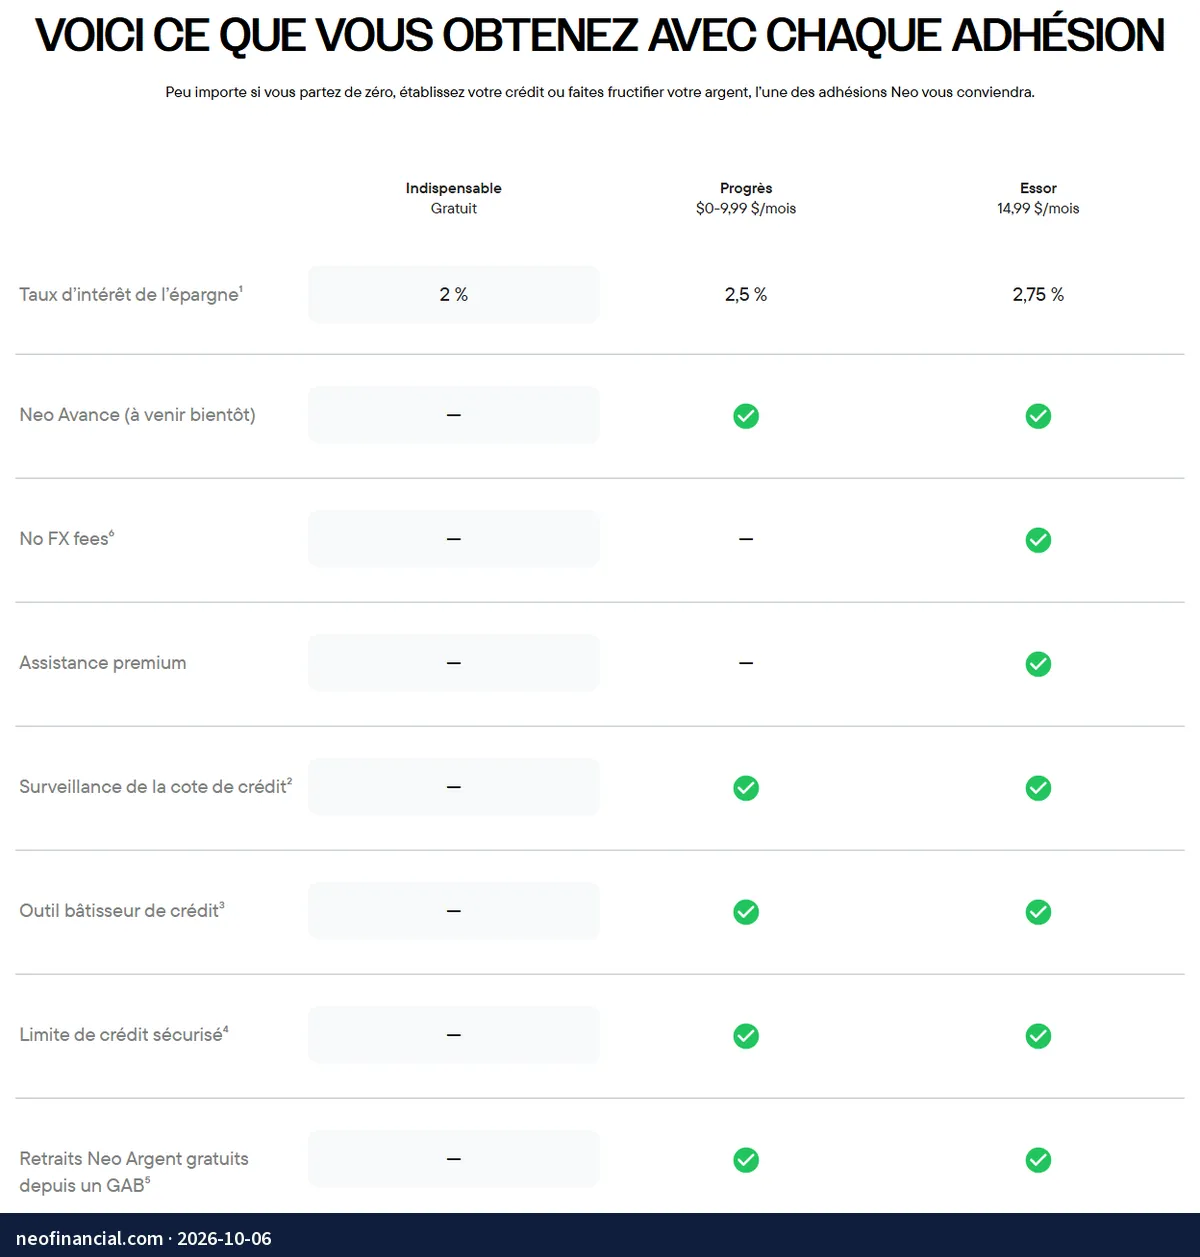
Neo Financial is a Canadian financial technology company, with no branches, that offers credit cards, accounts, investing managed by OneVest and mortgages. The Neo Chequing account has no monthly fees and earns cashback on everyday purchases; the Neo Savings account earns 2%, 2.5% or 2.75% depending on the membership: Essentials (free), Build (up to $9.99 per month) or Grow ($14.99 per month). Neo is not a CDIC member: funds in its accounts are held in trust at one or more member institutions and are eligible for CDIC protection up to $100,000. Neo is a money services business registered with FINTRAC and a payment service provider registered with the Bank of Canada. Live support is by chat, every day from 7 a.m. to 8 p.m. (Mountain Time). Neo is best suited to people who want cashback and interest-earning savings in a single app.
Fee Comparison Table
The Neo Chequing account has no monthly fees and no NSF fees. Neo memberships are free (Essentials) or cost up to $9.99 per month (Build) or $14.99 per month (Grow). Neo World Mastercard cards have no annual fee; Neo World Elite Mastercard cards cost $149 per year. Purchases in foreign currencies incur foreign exchange fees, except with the Grow membership (no FX fees, according to Neo’s membership table).
Detailed Scores
| Criterion | Score | Weight | Comment |
|---|---|---|---|
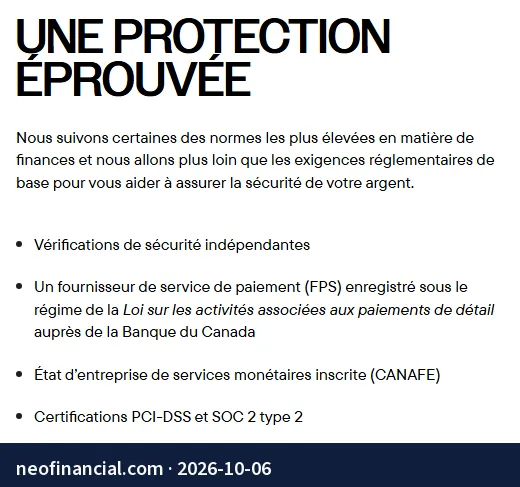
| Deposit insurance & regulatory compliance | 7/10 | 15 % | Neo Financial is not a bank and is not a CDIC member. Funds in Neo Chequing and Neo Savings accounts are held in trust, in the name of the primary account holder, at one or more CDIC member institutions; eligible funds are insured up to $100,000 per beneficiary, per member institution, provided certain disclosure rules are met. Neo does not name these institutions on its public pages. Neo is a money services business registered with FINTRAC and a payment service provider registered with the Bank of Canada. Neo Invest investments are not covered by CDIC; their assets are held by CI Investment Services, a member of CIRO and of the Canadian Investor Protection Fund. |
| Mobile & web app experience | 8/10 | 20 % | iOS and Android apps: 4.8/5 on the App Store (56K ratings) and 4.8/5 on Google Play (21.1K reviews). The app offers real-time spending tracking and categorization, real-time alerts, instant card lock and biometrics; mobile cheque deposit is announced as an upcoming feature. |
| Complementary products & services | 8/10 | 10 % | Neo offers the Neo Chequing account, with the Neo Money prepaid card, the Neo Savings account, several Mastercard credit cards (Neo Mastercard, with standard or secured credit; Neo World; Neo World Elite; United and Cathay co-branded cards), investing managed by OneVest (Neo Invest: TFSA, RRSP or personal account) and mortgages. Cashback is earned from more than 10,000 partners with the Neo Mastercard, and the Credit Builder tool requires the Build membership. |
| Security & fraud protection | 8/10 | 10 % | Neo highlights monitoring at all times, powered by artificial intelligence, real-time alerts, instant card lock, biometrics and Mastercard Zero Liability. It holds PCI-DSS and SOC 2 Type 2 certifications, and it is a payment service provider registered with the Bank of Canada and a money services business registered with FINTRAC. |
| Customer support | 6/10 | 10 % | Live chat is available every day from 7 a.m. to 8 p.m. (Mountain Time), and a virtual assistant answers at any time. Neo also offers a help centre and an online community where members and the Neo team answer. |
| Pricing & fees | 7/10 | 20 % | The Neo Chequing account has no monthly fees and no NSF fees. Memberships are free (Essentials) or cost up to $9.99 per month (Build) or $14.99 per month (Grow); depending on the membership, third-party ATM fees in Canada are reimbursed with the Neo Money card. Neo World Mastercard cards have no annual fee and Neo World Elite Mastercard cards cost $149 per year. Purchases in foreign currencies incur foreign exchange fees, except with the Grow membership (no FX fees, according to Neo’s membership table). |
| Interest rate & yield | 7/10 | 10 % | Neo Savings account: 2% with the Essentials membership (free), 2.5% with Build and 2.75% with Grow; Neo Chequing account: 0.1%. Interest is calculated daily on the closing balance and paid monthly; earnings on the Neo Savings account depend on the interest Neo earns on the funds and are paid at its discretion. Rates are subject to change without notice. |
| Transparency & governance | 6/10 | 5 % | Neo Financial publishes its account and card agreements, its disclosure statements and fee schedules, its privacy policy and its complaint resolution policy; its public pages present neither an annual report nor financial statements. Its account rates are dated and subject to change without notice. |
Strengths
- Credit cards, Neo Chequing and Neo Savings accounts, Neo Invest investing and mortgages in a single app.
- Cashback offers from more than 10,000 partners across Canada with the Neo Mastercard.
- Neo Chequing account with no monthly fees or minimum balance, with Interac e-Transfer payments, bill payments and direct deposit.
- App with real-time spending tracking and categorization, real-time alerts, instant card lock and biometrics.
- Funds in Neo accounts held in trust at CDIC member institutions, eligible for CDIC protection up to $100,000.
- PCI-DSS and SOC 2 Type 2 certifications.
Weaknesses
- Neo is not a CDIC member: protection, up to $100,000, covers funds held in trust at member institutions, provided certain disclosure rules are met.
- Neo Chequing account paying 0.1%; the 2.5% and 2.75% rates on the Neo Savings account require the Build or Grow membership.
- Live support by chat, every day from 7 a.m. to 8 p.m. (Mountain Time), with no one to answer outside these hours.
- Highest cashback (up to 5%) reserved for Neo World Elite Mastercard cards, at $149 per year.
Who Is It For?
- Canadian consumers who want to maximize cashback at partner retailers
- Users comfortable with a mobile app to manage their finances without a branch
- People looking for a free account with Interac transfers and direct deposit, with no minimum balance
- Profiles who want to combine chequing account, credit card, and investing in a single interface
- People who want to build their credit: the Neo Mastercard is available with a secured credit limit, and the Credit Builder tool requires the Build membership (up to $9.99 per month).
Not Ideal For…
- Savers who want the highest rate with no membership fee: the Neo Savings account earns 2% with the free membership, and 2.75% only with the Grow membership at $14.99 per month.
- Users who want to reach a person at any time: live chat is available every day from 7 a.m. to 8 p.m. (Mountain Time), and the virtual assistant at any time.
- People who carry a balance on their credit card, as interest can cancel out the cashback
- Customers who want a bank: Neo is a financial technology company that is not a CDIC member.
Alternatives
- EQ Bank — Personal Account that earns 1.00% base interest and 2.75% with a payroll direct deposit of at least $2,000 per month, at a CDIC member bank, with phone support.
- KOHO — Up to 2% cashback with the prepaid Mastercard; deposits eligible for CDIC coverage, up to $100,000, only with the Earn Interest option.
- Wealthsimple (chequing account) — Chequing account with no monthly fees, whose balance is protected by CDIC up to $1M through member institutions, in an app that also offers investing and trading.
How this review was conducted
This review is a documentary assessment. It is based on Neo Financial's public interface, its published pricing and publicly available information, as recorded on 2026-05-27. No field test was carried out: no subscription, no purchase and no exchange with customer support took place. Some items were checked again on 2026-10-06 against the official pages cited. Pricing and terms change: check them on Neo Financial's own site before you decide.
Documentary evaluation based on an analysis of the public interface, displayed pricing terms, and available public data. No purchase, actual subscription, or contact with support was made, and no usage period is reported. The scores reflect only the review of information published by Neo Financial and comparable neobanks.
Depending on the institution, this product falls under federal regulation (OSFI) or under that of Quebec's Autorité des marchés financiers (AMF). See our AMF disclosure page for more information.
Pricing information is indicative — verify current terms on the provider's website before subscribing. Affiliate disclosure.