EQ Bank Review 2026 — Account, Fees & Rates
Our Verdict
Overall score: 7.8/10. EQ Bank appeals to prudent savers thanks to its backing by a Schedule I bank, direct CDIC deposit insurance and its zero-fee pricing, but its offering does not include brokerage, unlike Wealthsimple.
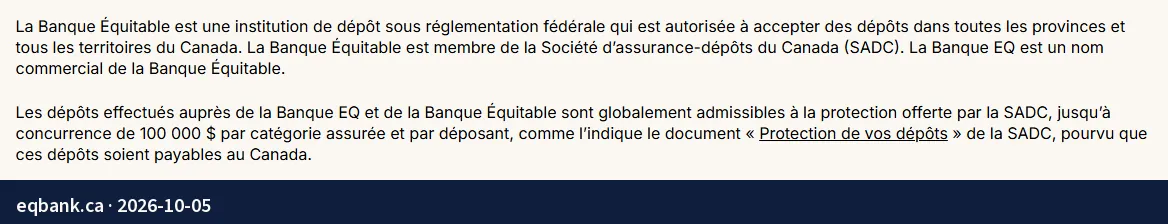
EQ Bank is a trade name of Equitable Bank, a Canadian Schedule I bank under federal regulation and a CDIC member: its deposits are eligible for CDIC protection up to $100,000 per insured category, per depositor. Its main strength is the yield on the Personal Account, which combines chequing and savings features: 1.00% base interest, and 2.75% with a payroll direct deposit of at least $2,000 per month. The absence of everyday banking fees, phone support and the transparency of a parent company listed on the Toronto Stock Exchange reinforce trust. On the other hand, the ecosystem offers neither brokerage, managed investing nor crypto-assets. Overall, the 7.8/10 score reflects a solid option for traditional savings, less suited to all-in-one profiles.
Fee Comparison Table
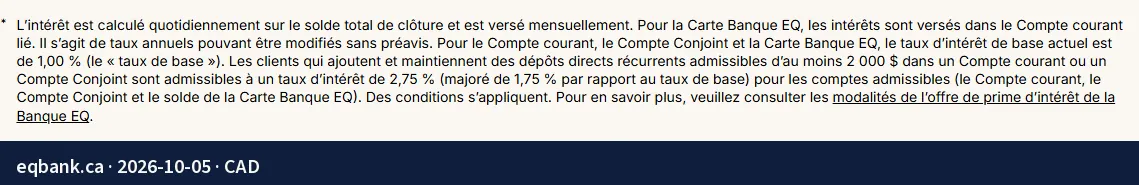
EQ Bank's Personal Account has no everyday banking fees: no account fees, no fees to send or receive Interac e-Transfers, and no bill payment, overdraft or inactive account fees. It earns 1.00% base interest, and 2.75% with a payroll direct deposit of at least $2,000 per month. The EQ Bank Card, a prepaid Mastercard, has no foreign exchange fees and earns 0.5% cashback; EQ Bank does not charge for ATM withdrawals in Canada and reimburses other operators' fees, up to five withdrawals per month and $5 each.
Detailed Scores
| Criterion | Score | Weight | Comment |
|---|---|---|---|
| Deposit insurance & regulatory compliance | 8/10 | 15 % | EQ Bank is a trade name of Equitable Bank, a federally regulated deposit-taking institution and a member of the Canada Deposit Insurance Corporation (CDIC). Deposits are eligible for CDIC protection up to $100,000 per insured category, per depositor. Its parent company, EQB Inc., describes Equitable Bank as a Schedule I bank. |
| Mobile & web app experience | 7/10 | 20 % | iOS and Android apps: 4.8/5 on the App Store (61K ratings) and 4.3/5 on Google Play (13.6K reviews). Interac e-Transfers, bill payments and automatic transfers between accounts are available in the app or online; the EQ Bank Card, a prepaid Mastercard, is loaded from the Personal Account. |
| Complementary products & services | 7/10 | 10 % | EQ Bank offers the Personal Account, a joint account, a US dollar account, 10- or 30-day notice savings accounts, TFSAs, FHSAs and RRSPs, 1- to 5-year GICs and mortgages, as well as the EQ Bank Card (prepaid Mastercard, 0.5% cashback) and a no-annual-fee PC Mastercard that earns PC Optimum points. It offers neither brokerage, managed investing nor crypto-assets. |
| Security & fraud protection | 7/10 | 10 % | Equitable Bank is a federally regulated deposit-taking institution and a CDIC member. EQ Bank publishes a bug bounty program and advice on protecting yourself against online scams; its public pages do not detail its authentication measures. |
| Customer support | 7/10 | 10 % | Phone support at 1-844-437-2265 and chat, every day from 8 a.m. to midnight (Eastern Time), with no service outside these hours. |
| Pricing & fees | 9/10 | 20 % | The Personal Account has no everyday banking fees: no account fees, no fees to send or receive Interac e-Transfers, and no bill payment, overdraft or inactive account fees. The EQ Bank Card has no monthly or annual fees and no foreign exchange fees; EQ Bank does not charge for ATM withdrawals in Canada and reimburses other operators' fees, up to five withdrawals per month and $5 each. |
| Interest rate & yield | 8/10 | 10 % | Personal Account: 1.00% base interest, raised to 2.75% with a payroll direct deposit of at least $2,000 per month; notice savings accounts: 2.35% (10 days) and 2.75% (30 days); 1- to 5-year GICs from 3.70% to 4.30%. Rates are annual, calculated daily, paid monthly and may change without notice. |
| Transparency & governance | 9/10 | 5 % | EQ Bank is a trade name of Equitable Bank, whose parent company, EQB Inc., is listed on the Toronto Stock Exchange (TSX: EQB) and publishes its quarterly results, MD&A and supplemental financial and regulatory information. Rates displayed on eqbank.ca may change without notice. |
Strengths
- Direct CDIC deposit insurance in its own name through Equitable Bank, a Schedule I bank regulated by OSFI, with coverage of CAD 100,000 per insurable category.
- Zero-fee pricing: no monthly fees, no minimum deposit, unlimited free e-Transfers, ATM fees reimbursed in Canada, and no foreign exchange fees on the card.
- Personal Account at 2.75% with a payroll direct deposit of at least $2,000 per month (1.00% without), and notice savings account at 2.35% (10 days) or 2.75% (30 days).
- US dollar account paying 2.50% interest.
- Phone (1-844-437-2265) and chat support, every day from 8 a.m. to midnight (Eastern Time).
- Transparency of a company listed on the Toronto Stock Exchange, with public annual reports and quarterly financial statements.
Weaknesses
- ATM fee reimbursement limited to five withdrawals per month, up to $5 each.
- Ecosystem without stock brokerage, managed investments or crypto, unlike Wealthsimple.
- Cashback limited to 0.5% on purchases with the EQ Bank Card, versus up to 2% at KOHO.
- Customer support not available 24/7.
Who Is It For?
- Prudent savers who want direct CDIC deposit insurance through a Schedule I bank regulated by OSFI.
- Customers looking for a hybrid chequing and savings account that pays interest with no monthly fees and no minimum deposit.
- People who prioritize real estate lending and Equitable Bank's mortgage ecosystem.
- Users who want phone and chat support, every day from 8 a.m. to midnight (Eastern Time).
- Customers who value the transparency of a publicly listed company with public reports and quarterly financial statements.
Not Ideal For…
- Self-directed investors who want a combined account with brokerage and managed investments, as at Wealthsimple.
- Users looking for high cashback: the EQ Bank Card earns 0.5%, versus up to 2% at KOHO.
- People who cannot have their pay deposited directly (at least $2,000 per month): without it, the Personal Account earns 1.00% instead of 2.75%.
- Customers who demand 24/7 customer support, which EQ Bank does not offer.
Alternatives
- Wealthsimple Cash — Chequing account with no monthly fees, whose balance is protected by CDIC up to $1M through member institutions, in an app that also offers investing and trading.
- KOHO — Up to 2% cashback with the prepaid Mastercard; deposits eligible for CDIC coverage, up to $100,000, only with the Earn Interest option.
- Neo Financial — Canadian neobank that highlights CDIC deposit insurance.
How this review was conducted
This review is a documentary assessment. It is based on EQ Bank's public interface, its published pricing and publicly available information, as recorded on 2026-05-27. No field test was carried out: no subscription, no purchase and no exchange with customer support took place. Some items were checked again on 2026-10-05 against the official pages cited. Pricing and terms change: check them on EQ Bank's own site before you decide.
Strictly documentary evaluation conducted based on the public interface, the displayed pricing conditions and public regulatory and financial data. No actual purchase or subscription was made, and no test duration or real service relationship was measured.
Depending on the institution, this product falls under federal regulation (OSFI) or under that of Quebec's Autorité des marchés financiers (AMF). See our AMF disclosure page for more information.
Pricing information is indicative — verify current terms on the provider's website before subscribing. Affiliate disclosure.